E-invoicing, or digitised invoicing processes, ensure that invoices are processed more quickly, efficiently and accurately. For businesses, one date is coming into sharp focus: from 1 January 2027, it will be compulsory in Germany to actively issue e-invoices in the B2B sector – initially for businesses with a turnover of over 800,000 euros in the previous year, and from 2028 for all businesses. 

      The obligation to receive e-invoices has been in place since 2025 and has been implemented in many places. The decisive step now is to move towards audit-proof transmission and stable, error-resilient processes – this is where the biggest gaps still lie in practice. 
      Why act now?

      The timeframe up to 2027 is tighter than it appears at first glance:

      • Time remaining: Conceptualisation, system selection, implementation, testing and training all require lead time – particularly in corporate groups with complex system landscapes. 
      • Multiple jurisdictions: Other EU Member States are also introducing mandatory e-invoicing or e-reporting (including Slovakia and Norway) or have already done so (including Belgium, Croatia, Poland and France). Companies operating internationally need a coordinated strategy rather than individual projects.
      • Involve the tax function at an early stage: Expertise on invoice content, legal requirements and audit trails must be incorporated into the project from the outset. 
      • Looking beyond 2027: E-invoicing is not an end in itself, but the foundation for EU-wide e-reporting under ViDA (from 1 July 2030). Germany, too, is planning to introduce a national reporting system from 1 July 2030, in line with ViDA. Those who set things up properly now will also be well-prepared for the next step.

      E-invoicing: Key facts at a glance

      What is an e-invoice?

      An electronic invoice (e-invoice) is an invoice that is issued, transmitted and received in a structured electronic format and which allows for electronic processing. An invoice in PDF format does not meet this requirement.

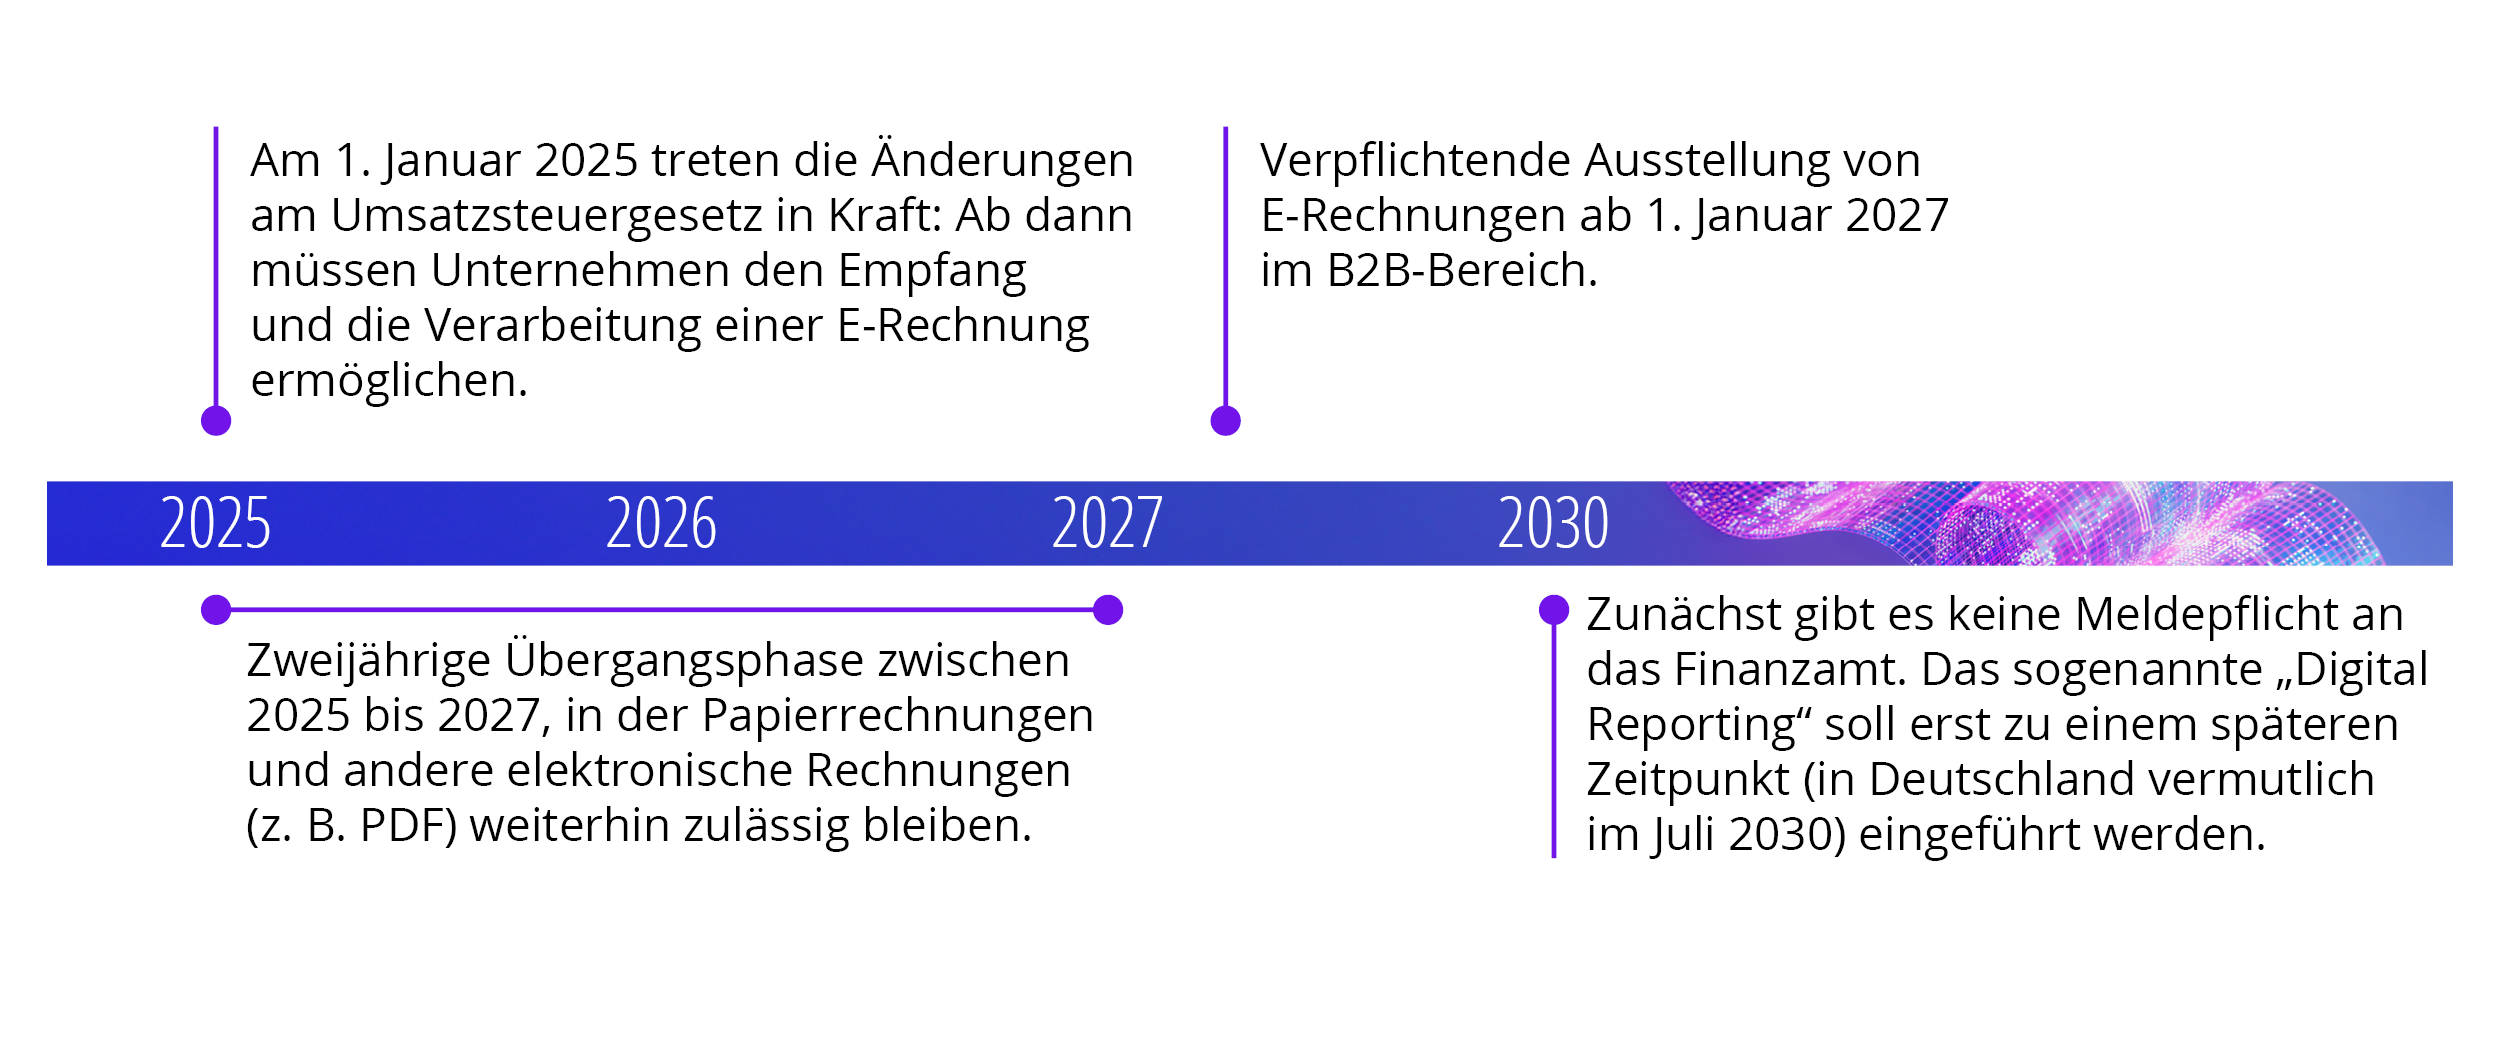
      Timetable

      Transition period until 2027

      E-Rechnung Zeitstrahl

      An overview of the key points of e-invoicing

      • Mandatory introduction of the EN16931 invoice format (European CEN standard from the Business-to-Government sector (B2G)); this means that the XRechnung and ZUGFeRD formats already in use today will, in principle, also be permitted for the B2B sector.
      • The EDI (Electronic Data Interchange) process using other electronic formats will remain permissible on a permanent basis, provided that data can be extracted into EN16931 or into a format interoperable with EN16931.
      • There are also exceptions. There is no obligation to issue e-invoices for:
        • Small-value invoices up to a maximum of 250 EUR
        • Invoices for travel tickets
        • Tax-exempt transactions without the right to deduct input VAT
        • B2C transactions

      Ready to talk?

      Newsticker

      New version ZUGFeRD 2.5 / Factur-X 1.09 released

      The German Electronic Invoicing Forum (FeRD), in collaboration with its French counterpart, has released the new joint version of the hybrid e-invoicing format ZUGFeRD 2.5 and Factur-X 1.09. It updates code lists and validation artefacts to comply with EN 16931:2026 and adds new data elements to the EXTENDED profile. ZUGFeRD 3.0 is due to be published in spring 2027 and will adopt the same sequential numbering as the French standard Factur-X. This update is intended to ensure full implementation of EN 16391 2026.

      Syntax bindings for EN 16931 – technical implementation expected

      The updated syntax bindings for EN 16931-1:2026, which was updated in March, are expected in summer 2026. They set out binding rules on how the semantic content of the standard is to be technically represented in the common XML formats UBL (version 2.5) and UN/CEFACT CII (D25A). They thus form the basis for a uniform European implementation of e-invoicing. For businesses, these bindings are crucial for ensuring that e-invoices are generated, validated and processed in accordance with the standard.

      XRechnung 4.0 – new version of the core standard in the pipeline

      XRechnung 4.0 is a new version of the German e-invoicing standard currently being developed, which is closely aligned with the revised EN 16931:2026. Plans include expanded data content, improved interoperability with other European formats and technical updates. Businesses should follow the roadmap and assess in good time which system and process adjustments will be required for the transition. A first draft is expected in summer 2026, with the final version scheduled for autumn 2026.

      France introduces mandatory e-invoicing – transition period expectedIn

      In France, mandatory e-invoicing for large companies will come into force on 1 September 2026 – with smaller companies following in stages. A transition period is expected to last until 1 January 2027: Companies that demonstrate ‘good faith’ in implementing the system are not expected to face fines from the French tax authorities (DGFiP). The French model is considered particularly complex, as e-reporting to the tax authorities requires the mandatory use of an external, approved platform provider (‘Plateforme Agréée’, PA), through which the entire reporting process is handled.

      Norway introduces mandatory B2B e-invoicing

      In June 2026, the Norwegian Parliament passed legislation making B2B e-invoicing mandatory. From 1 January 2027, all businesses required to keep accounts – including foreign companies registered for VAT in Norway – must be able to send structured e-invoices in EHF 3.0 format via the Peppol network, provided the recipient is listed in the ELMA register. PDF invoices sent by email will then no longer be permitted. Micro-enterprises with an annual turnover of less than NOK 50,000 are exempt. In a second phase, starting on 1 January 2030, the obligation to receive e-invoices and to maintain fully digital accounts will come into force.

      Luxembourg publishes draft bill on e-invoicing

      Luxembourg has tabled a draft bill on mandatory B2B e-invoicing (parliamentary procedure to follow after the summer recess). This applies to domestic B2B transactions between two registered, resident companies. From 1 January 2028, all businesses must be able to receive e-invoices; the obligation to issue e-invoices will be phased in from 1 January 2028 (large businesses) and 1 January 2029 (smaller businesses). Peppol is designated as the network; as a transitional measure, alternative solutions are available via the government portal (subject to a fee per invoice).

      UK plans to introduce mandatory e-invoicing in accordance with the Peppol standard

      In June 2026, the UK government confirmed that the future mandatory e-invoicing scheme in the United Kingdom will be processed via the Peppol network. The plan is to adopt a decentralised model without real-time reporting to HMRC, similar to the Belgian approach. The requirement is set to apply to B2B and B2G transactions from 1 April 2029. Businesses with commercial relationships with the UK should consider connecting to a Peppol Access Point at an early stage.

      What companies should do now

      Because of the rapidly evolving heterogeneous regulatory landscape, companies should develop a global strategy for e-invoicing and digital reporting. You can read about which points to take into account in our Klardenker article

      In addition to developing a strategy, very concrete steps are required:

      • Analysing and adapting processes

        Review existing Enterprise Resource Planning (ERP) systems, analyse your invoicing processes, develop cross-country solutions (ERP-integrated and/or via the involvement of a service provider) and maintain the master data of your creditors and debtors.

      • Development of a digitalisation strategy

        Develop a digitalisation strategy, especially if your company has primarily used analogue invoice formats up to now.

      • Communication with business partners

        Inform suppliers and customers early on about the upcoming changes and the new requirements.

      How we support you

      Our team of tax experts will be happy to assist you in preparing for e-invoicing, from identifying your requirements right through to selecting and implementing the solution that best suits your needs.

      Our colleagues from Digital Process Compliance also support you in adapting and creating digital processes and, as auditors, determine the robustness and conformity of your processes. Our experts support you in the transition to electronic invoice formats and in adapting your processes and internal control system.


      Download

      E-Rechnungen rechtssicher, effizient und zukunftsfähig umsetzen

      E-Rechnungseingang testen - mit praxisnahem Testpaket und fachlicher Unterstützung

      Is your business ready for e-invoicing?

      Find out in ten minutes with our free Readiness Check and receive your assessment straight away.

      Digital patterns

      More KPMG insights for you

      Your contacts